• Link to Facebook
  • Link to X
  • Link to Instagram
  • Link to Youtube
  • Link to LinkedIn
  • Link to Mail
Free PDF: The 15-Minute Swing Trader's Checklist, the daily routine on the record since 2014
Synapse Trading
  • Mentoring
    • Trading Mastery Program
    • All mentoring options
  • Signals
    • Daily trading signals
    • Signals trade log
  • Results
    • Student results and testimonials
    • Public trade log, losses left in
  • Free guides
    • Start here
    • Trading foundations
    • Technical analysis
    • Strategies and systems
    • Risk and money
    • Trading psychology
    • Markets and products
    • Free trading guides
    • Tools and resources
    • Blog
  • About
    • My background
    • My trading journey
    • Media and interviews
    • Travel log
  • Contact
    • Contact me
    • Partnerships
  • Start free
  • Click to open the search input field Click to open the search input field Search
  • Menu Menu
Spencer Li

The Psychology of Money Summary: Morgan Housel’s Lessons for Traders

Trading Foundations
The Psychology of Money - book summary

Twenty short chapters on why behaviour beats intelligence with money, and the three lessons that matter most if you trade

Published: 17 October 2026 · Last updated: 4 October 2026 · By Spencer Li, CFTe


What is The Psychology of Money about? Morgan Housel’s book argues that “doing well with money has a little to do with how smart you are and a lot to do with how you behave.” He describes the subject as “a soft skill, where how you behave is more important than what you know.” The book is 20 short chapters, each a standalone story, and you can read them in any order.

For a trader, three ideas carry the most weight. Survival comes before returns, because compounding only works if you stay in the game. A few outsized wins drive most results, so being wrong often is normal. And room for error, in your sizing and your savings, is what lets you survive the surprises nobody forecasts. This summary walks through those three, plus the other chapters worth your time.
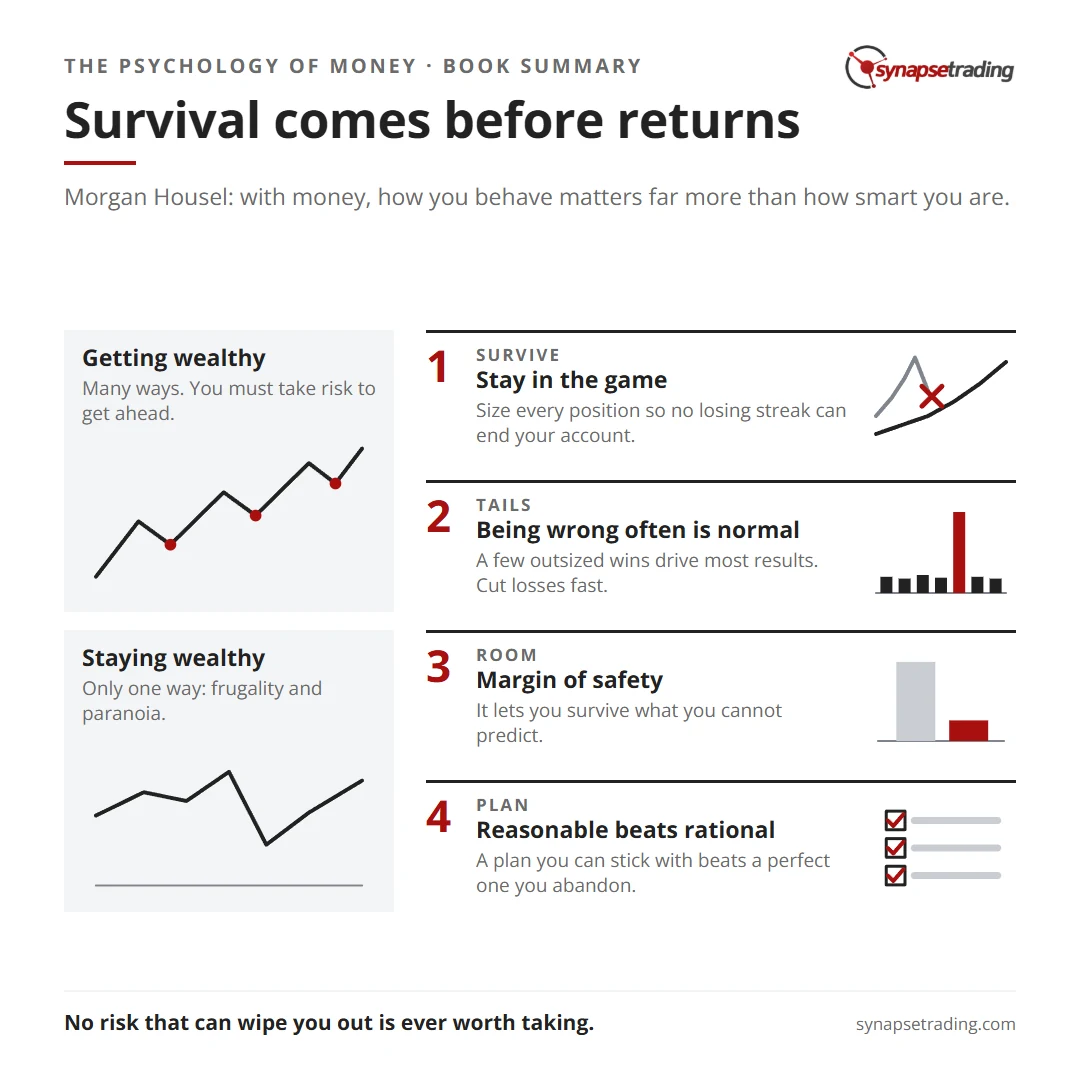
Survival comes before returns. Summary card for the post: The Psychology of Money Summary: Morgan Housel's Lessons for Traders.

Who is Morgan Housel?

Morgan Housel is a writer and investor at Collaborative Fund, a venture firm he refers to in the book as his own. The book grew out of a 2018 report he wrote on 20 flaws, biases and causes of bad money behaviour, which was read by over one million people. Some short passages from that report appear in the book unchanged.

His style is the reason the book works. He tells a story, draws one point from it, and moves on. There are no formulas to memorise.

What is the overview of the book?

Housel’s premise is that the standard financial curriculum, with its emergency funds and savings rates and correlations, is not wrong. It is beside the point. As he puts it, knowing what to do “tells you nothing about what happens in your head when you try to do it.”

Here are the chapters that matter most to a trader, and the one-line idea in each.

ChapterThe idea in one line
1. No One’s CrazyYour own experience shapes how you see markets far more than the data does
2. Luck & RiskOutcomes are shaped by forces beyond effort, so judge decisions, not results
3. Never EnoughRisking what you need for what you do not need is foolish
4. Confounding CompoundingTime, not the highest return, does the heavy lifting
5. Getting Wealthy vs. Staying WealthyGetting money and keeping it are opposite skills
6. Tails, You WinA small minority of events drives most outcomes
11. Reasonable > RationalA good plan you can stick with beats a perfect one you abandon
13. Room for ErrorMargin of safety lets you survive what you cannot predict
15. Nothing’s FreeVolatility is the fee for returns, not a fine
16. You & MeDo not take cues from people playing a different game

The three lessons traders should take

Why is staying in the game the whole point?

Chapter 5 opens with the story every trader should know. In the 1929 crash, Jesse Livermore, “the greatest stock market trader of his day,” was short. His family met him in tears on October 29th, expecting ruin, and he told them they were rich. Then, overflowing with confidence, he made larger and larger bets, went deep into debt, and lost everything.

Housel’s line on it is simple. There are many ways to get wealthy, but “there’s only one way to stay wealthy: some combination of frugality and paranoia.”

He sets Livermore against Warren Buffett. About 99.6% of Buffett’s net worth, by the book’s numbers, came after his 50th birthday. “His skill is investing, but his secret is time.” And the reason Buffett had the time is that he never blew up. “He survived. Survival gave him longevity.”

So the rule Housel takes from it is the same idea our low-risk approach is built on: “More than I want big returns, I want to be financially unbreakable.” In trading terms, that means sizing every position so that no losing streak can end your account. The risk management guide shows how we do that in practice.
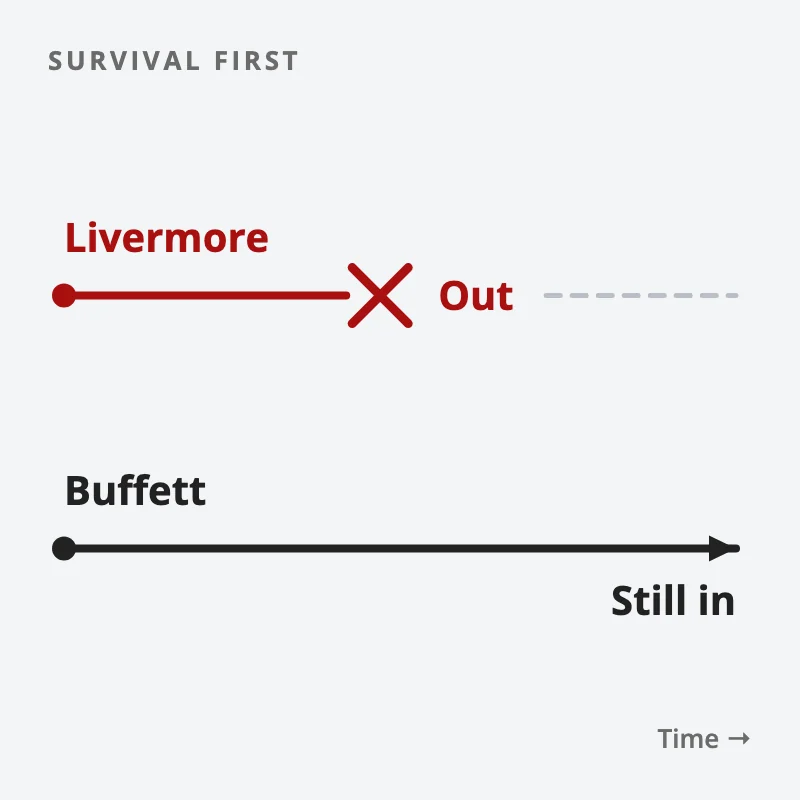
Two lines through time: Livermore's ends early in a blow-up and he is out, while Buffett's keeps going because he survived
Compounding only works if you stay in the game, so survival comes before returns.

Why is being wrong often normal?

Chapter 6 is the most useful chapter in the book for anyone who hates losing trades.

Housel shows that a tiny share of events drives most results. In one study of more than 21,000 venture financings, 65% lost money, and half a percent earned 50 times or more. In the Russell 3000 index since 1980, 40% of companies lost at least 70% of their value and never recovered. Effectively all of the index’s returns came from the 7% that did extremely well.

Even the best investors live with this. Buffett said he has owned 400 to 500 stocks in his life and made most of his money on 10. Peter Lynch put it bluntly: “If you’re terrific in this business, you’re right six times out of 10.”

For a trader, this is the case for cutting losses fast and letting winners run. Your win rate can be modest if your winners are much larger than your losers. Our post on win rate vs risk reward works through the numbers.

Why does margin of safety matter more than a forecast?

Chapter 13 starts with blackjack card counters. A counter with roughly a 2% edge over the casino still loses 49% of the time, so they need a big enough bankroll to ride out the bad runs. The edge is real. Without room for error, it does not matter.

Housel borrows Benjamin Graham’s line: “the purpose of the margin of safety is to render the forecast unnecessary.” And he draws a hard line on leverage. You must take risk to get ahead, but “no risk that can wipe you out is ever worth taking.”

The book’s starkest example is Rick Guerin, Buffett and Munger’s third partner. He was on margin going into 1973 to 1974, when the market fell almost 70%, and he was forced to sell his Berkshire shares to Buffett. He was just as smart as the other two, Buffett said. He was simply in a hurry.

What else in the book is worth your time?

Chapter 11, Reasonable > Rational. “You’re not a spreadsheet. You’re a person. A screwed up, emotional person.” Housel says to “aim to just be pretty reasonable.” A strategy you can stick with through its lean years beats a perfect one you abandon at the first drawdown.

Chapter 15, Nothing’s Free. The price of market returns “is not dollars and cents. It’s volatility, fear, doubt, uncertainty, and regret.” Treat it as a fee you pay, not a fine for doing something wrong, and you stop trying to dodge it.

Chapter 16, You & Me. “Investors often innocently take cues from other investors who are playing a different game than they are.” A day trader’s opinion on a stock is useless to a long-term holder, and the reverse is true too. Know which game you are in.

Chapter 6 again, on timing. Housel’s example of three savers, Sue, Jim and Tom, from 1900 to 2019 is worth the read. Sue kept investing through every recession. Jim and Tom tried to step aside. Sue ended with about 69% more than Jim and about 86% more than Tom.

What did readers take from it?

The book reaches people well outside trading. A Singapore investor on Reddit, writing in May 2026, said the book taught them about diversification, tail events and rebalancing, and above all about “sleeping well at night.”

That line is close to Housel’s own. In the chapter on room for error, he quotes Buffett: “When forced to choose, I will not trade even a night’s sleep for the chance of extra profits.”

Concluding thoughts

Housel is honest about his own limits. In the last chapter he admits that two of his largest positions, a house with no mortgage and a large cash holding, are hard to defend on paper. He holds them because they let him sleep. His summary chapter puts the whole book in one admission: “I can’t tell you what to do with your money, because I don’t know you.”

For traders, the book will not give you a setup or an entry rule. What it gives you is the reason your rules matter. If you want the theory of value investing that Housel challenges in chapter 12, read our summary of The Intelligent Investor. For a book on spending your money well once you have it, see our summary of Die With Zero. The full list of recommended books is in the best investing and trading books of all time, and the habits behind staying calm are in the trading psychology guide.

So here is the question Housel leaves you with. If your account fell by a third tomorrow, would your plan survive it, and would you?

If you want a daily routine built around surviving first, our free 15-Minute Swing Trader’s Checklist lays it out. Get the free checklist →

FAQ

What is the main message of The Psychology of Money?

That doing well with money depends far more on how you behave than on how smart you are. Housel calls it a soft skill, and builds the case through 20 short stories.

Is The Psychology of Money good for traders?

Yes, for the mindset rather than the method. Its chapters on survival, tail outcomes and room for error map directly onto position sizing and cutting losses.

What does Housel say about risk?

He says no risk that can wipe you out is worth taking, and that margin of safety, not a good forecast, is what lets you survive the surprises.

How long is The Psychology of Money?

It has 20 short chapters plus an introduction and a postscript, and each chapter stands alone, so you can read it in any order.

What is the Livermore story in The Psychology of Money?

Jesse Livermore made a fortune shorting the 1929 crash, then grew overconfident, took ever-larger leveraged bets and lost everything. Housel uses him to show that getting wealthy and staying wealthy are different skills.

Go deeper

Housel explains why survival comes first. The free 15-Minute Swing Trader’s Checklist shows how we build it into every trade: the daily scan, the questions to ask before you enter, and the five rules that keep you in the game.


About the author. Spencer Li is The 15-Minute Trader and the founder of Synapse Trading. He is a Certified Financial Technician (CFTe) with 15+ years of trading, run from 70+ countries. He holds a B.Acc and B.BM from SMU. Every trade he takes is public, dated, losses left in. He teaches low-risk swing trading in 15 minutes a day, one system for any market.

Educational content only, not personalised financial advice. Trading carries risk, including loss of capital. Past performance is not indicative of future results. Synapse Trading is not licensed or regulated by MAS.
by Spencer Li
https://synapsetrading.com/wp-content/uploads/2026/10/psychology-of-money-summary-card.webp 630 1200 Spencer Li https://synapsetrading.com/wp-content/uploads/2026/10/synapse-logo-horizontal-light.png Spencer Li2026-07-21 10:52:252026-10-04 18:14:53The Psychology of Money Summary: Morgan Housel’s Lessons for Traders
Spencer Li

Trading Your Own Money vs Trading for a Fund: What Actually Changes

Trading Foundations
Your money vs a fund - prop trading

The rules, the clock and the money all change hands when you join a fund, and so does the way a losing week feels

Published: 17 October 2026 · Last updated: 26 September 2026 · By Spencer Li, CFTe


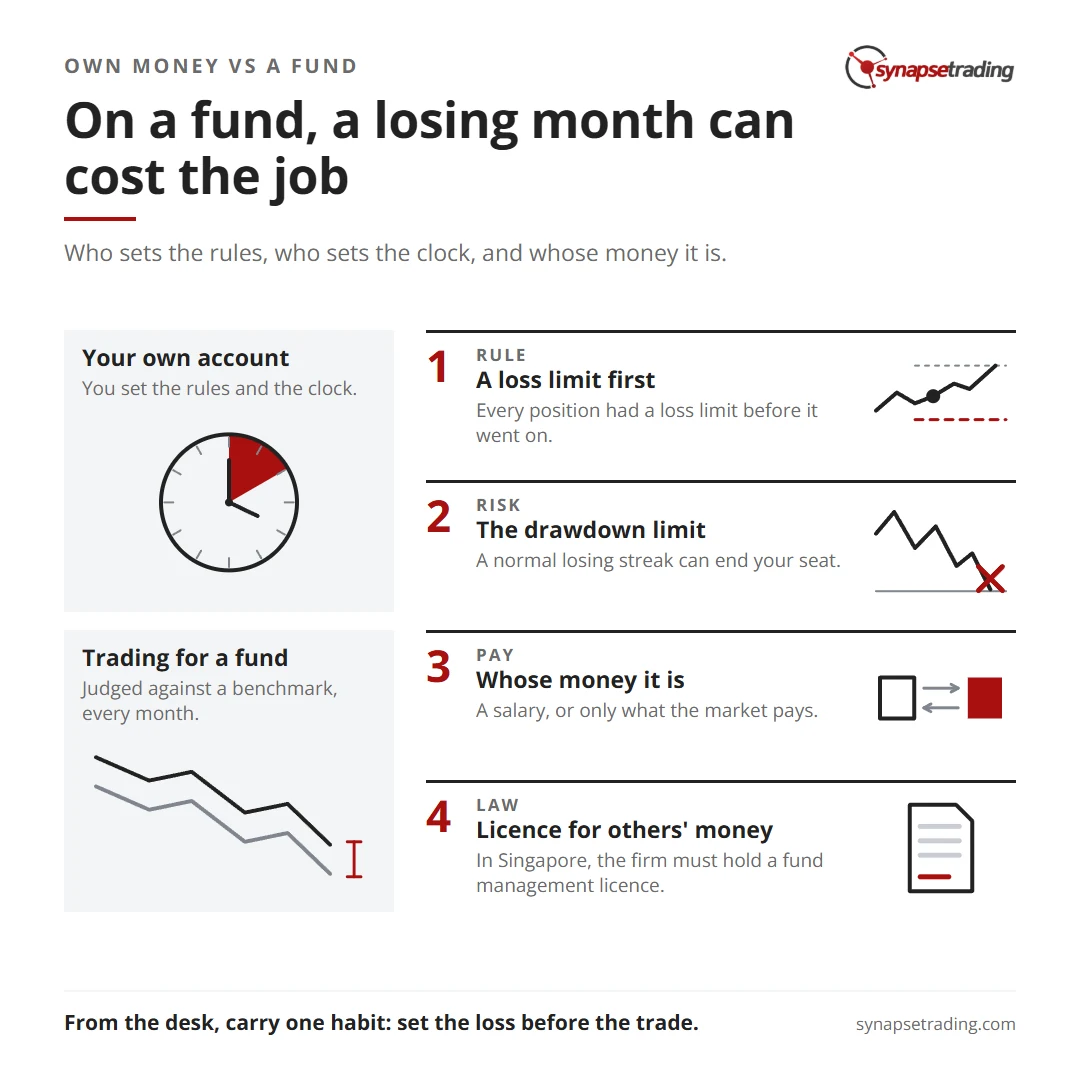
What changes when you trade for a fund instead of your own account? Three things change hands. On a fund, someone else writes the rules: your loss limits, what you may trade, how big you can go. Someone else sets the clock: you are judged monthly against a benchmark, and a drawdown limit can end your seat. And it is someone else’s money, which means a salary and a share of profits instead of all of the gains and all of the losses.

The trading itself, the charts and the setups, can look almost the same. What changes is what a losing month costs you. On your own account, it costs money. On a fund, it can cost you the job. I traded professionally for a few years before going independent, so I have sat on both sides of it.

On a fund, a losing month can cost the job. Summary card for the post: Trading Your Own Money vs Trading for a Fund: What Actually Changes.

What changes when you trade for a fund?

Here is the short version, side by side.

Your own accountTrading for a fund
Who sets the rulesYouThe fund and its risk manager
Loss limitWhatever you decide, or noneSet before each position, plus a drawdown limit on the book
How you are judgedYour own returnReturn against a benchmark, every month
Worst caseYou lose capitalYou lose capital and possibly the seat
PayOnly what the market paysSalary, bonus or profit share
Can you sit in cash?Yes, for as long as you likeOften hard, if the benchmark is rising
Licence in SingaporeNone needed for your own moneyThe firm must hold a fund management licence

The rest of this post walks through why each row matters: who sets the rules, who sets the clock, and whose money it is.

Who decides when you are wrong?

On your own account, you decide. That sounds like freedom, and for most new traders it is the problem. You can move a stop, add to a loser, or skip a rule after three bad trades, and nobody will stop you.

On a desk, those decisions are taken out of your hands before the trade goes on. As our career in trading guide puts it, every position had a loss limit before it went on, and the risk manager asked one question. How much can this lose?

A rule written before the trade does its work when your judgement is at its worst, in the middle of a loss.

Now the catch. Rules written for a fund are written for the fund’s book, size and investors. Some of them do not fit a single person with a small account. When you go independent, you have to write your own rules, keep the ones that protect you, and drop the ones that only made sense for someone else’s money. The risk management guide lays out the rules we teach now.

How are you judged, and how often?

On your own account, the only clock is your own. A flat quarter is a flat quarter.

On a fund, you are measured against a benchmark, usually an index the fund is trying to beat. Say the market is up 20% in a year and you are up 12%. On your own account, 12% is a good year. On a fund, you are 8 points behind, and someone will ask you why.

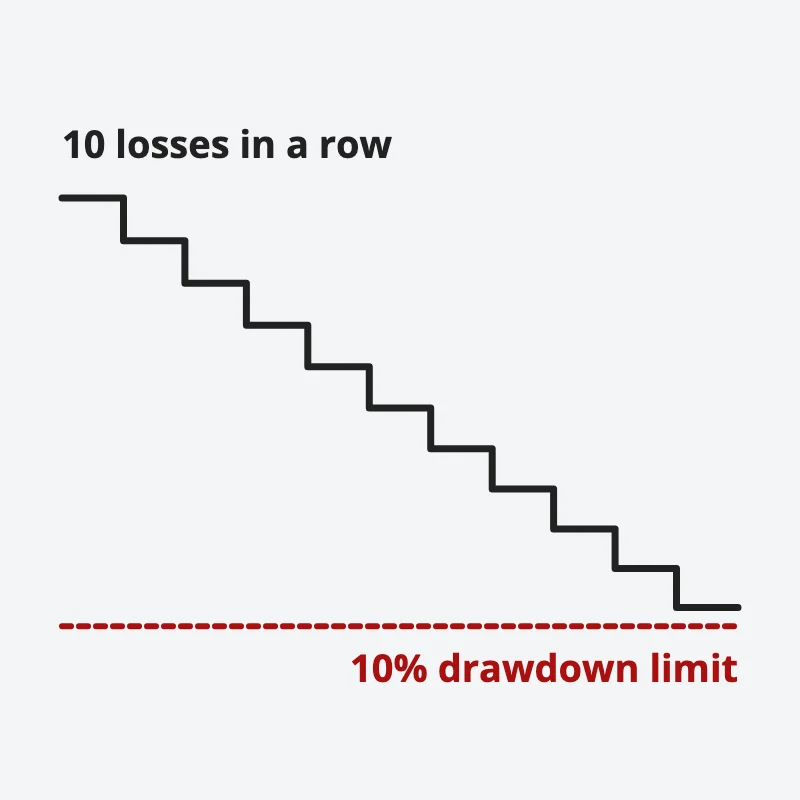
The drawdown limit is the other clock. Here is how fast it can run. Say you risk 1% of the book on each trade, and the fund’s limit is a 10% drawdown. Ten losers in a row take you down 9.6%. On your own account, that is a bad month you can learn from. Under that limit, it is a meeting about your future. People underestimate this part when they picture a desk. The same ten losses a private trader can absorb and study become, on a fund, a number on a report that someone above you reads before anything else about you.

Ten losses in a row step the account down to just above the fund's 10% drawdown limit
On a fund, a normal losing streak can bring you to the drawdown limit that ends your seat.

And losing streaks of that length happen to good systems. Our post on whether trading is skill or luck shows how many trades you need before a run of losses tells you anything at all.

The clock also changes how you spend your day. The only time I was glued to the screen was when I was trading for a fund, very early in my career. On my own account, I trade end-of-day, in about 15 minutes. That is a choice a desk rarely lets you make.

What changes when the money is not yours?

Two things change. The pay and the feeling.

The pay first. Our post on career paths for the trading professional sets out how each role is paid, from salary and bonus to a profit share. On your own account there is no salary. The market pays you, in lumps, with gaps.

The feeling is harder to describe. Some traders find it easier to cut a loss on someone else’s money, because it is not their rent. Others freeze, because the loss is also a mark against their name, and that fear can make a trader hold a loser longer than they would with their own savings, hoping it comes back before anyone looks. Either way, a rule set before the trade helps, because the decision is already made when the loss arrives.

On your own account, every loss is personal. There is no risk manager to blame and no salary to soften it. That is why the rules you write for yourself need to be just as firm as a desk’s.

Can you trade other people’s money without joining a fund?

In Singapore, only through a licensed firm. The Monetary Authority of Singapore (MAS) says: “A company must hold a fund management licence to conduct fund management activities under the Securities and Futures Act 2001”.

So “I’ll just manage my friends’ money” is a regulated activity in Singapore, however small the sum and however close the friends. If you want to run money for others, check the MAS licensing pages first.

A trader on Reddit wanted the best of both: “Partnering with institutions/Hedge funds etc. while keeping full control of a trading system.” It is a common wish. In practice, the more of other people’s money you take, the more of the control you hand over. That trade-off is the whole subject of this post.

The other route people try is the “funded account”. Our post on prop firm challenges explains how that model works and what to check before you pay a fee.

If you trade your own money and want a routine that gives you desk-style discipline without the desk, our free 15-Minute Swing Trader’s Checklist has the questions to ask before every trade. Get the free checklist →

So which is better, your own money or a fund’s?

Neither is better in general. They train different things. A fund trains discipline, because the rules are not optional. Your own account trains independence, because nobody writes the rules for you.

The habit worth carrying from the desk is setting the loss before the trade. The freedom worth using on your own account is the right to wait, size small and trade on your own clock.

So try this before your next trade. If a risk manager were standing behind you, what is the one question they would ask? And do you have an answer?

FAQ

Is trading for a fund easier than trading your own money?

It is more structured. The fund sets loss limits and position sizes for you, but you are also judged against a benchmark and can lose your seat after a drawdown.

Do fund traders have loss limits?

Yes. Positions carry a loss limit set before the trade, and the book as a whole usually has a drawdown limit set by the fund.

Do I need a licence to manage other people’s money in Singapore?

Generally, yes. MAS says a company must hold a fund management licence to conduct fund management activities under the Securities and Futures Act 2001. Check MAS’s licensing pages for your own situation.

How are fund traders paid?

Usually through a salary plus bonus, or a profit share, depending on the role. On your own account, you are paid only by your trading results.

Can I trade end-of-day on a fund?

It depends on the fund and the role. Many desk roles expect you at the screen through the session. On your own account, you choose your timeframe.

Go deeper

Desk discipline does not need a desk. The free 15-Minute Swing Trader’s Checklist gives you the daily scan, the questions to ask before every trade, and the five rules that keep you in the game.


About the author. Spencer Li is The 15-Minute Trader and the founder of Synapse Trading. He is a Certified Financial Technician (CFTe) with 15+ years of trading, run from 70+ countries. He holds a B.Acc and B.BM from SMU. Every trade he takes is public, dated, losses left in. He teaches low-risk swing trading in 15 minutes a day, one system for any market.

Educational content only, not personalised financial advice. Trading carries risk, including loss of capital. Past performance is not indicative of future results. Synapse Trading is not licensed or regulated by MAS.
by Spencer Li
https://synapsetrading.com/wp-content/uploads/2026/10/trading-own-money-vs-fund-card.webp 630 1200 Spencer Li https://synapsetrading.com/wp-content/uploads/2026/10/synapse-logo-horizontal-light.png Spencer Li2026-07-08 11:27:382026-09-26 07:07:03Trading Your Own Money vs Trading for a Fund: What Actually Changes
Spencer Li

How to Make Money in Stocks Summary: William O’Neil’s CAN SLIM Rules

Trading Foundations
O'Neil's CAN SLIM rules - book summary

The seven letters O’Neil drew from a century of big winners, the 7% to 8% loss rule that protects them, and when he takes profits

Published: 17 October 2026 · Last updated: 18 August 2026 · By Spencer Li, CFTe


What is How to Make Money in Stocks about? William O’Neil’s book sets out one system for buying growth stocks, called CAN SLIM, and the selling rules that make it work. He built it by studying the biggest stock market winners of each year and asking what they looked like just before they ran.

The answer fits in seven letters. Buy companies with surging current and annual earnings, something new, and strong demand for their shares. Buy the leader in its group, owned by good funds, in a rising market. Then cut every loss at 7% or 8% below your cost, with no exceptions. This summary walks through each letter, the loss and profit rules, and where the evidence is weaker than the book admits.

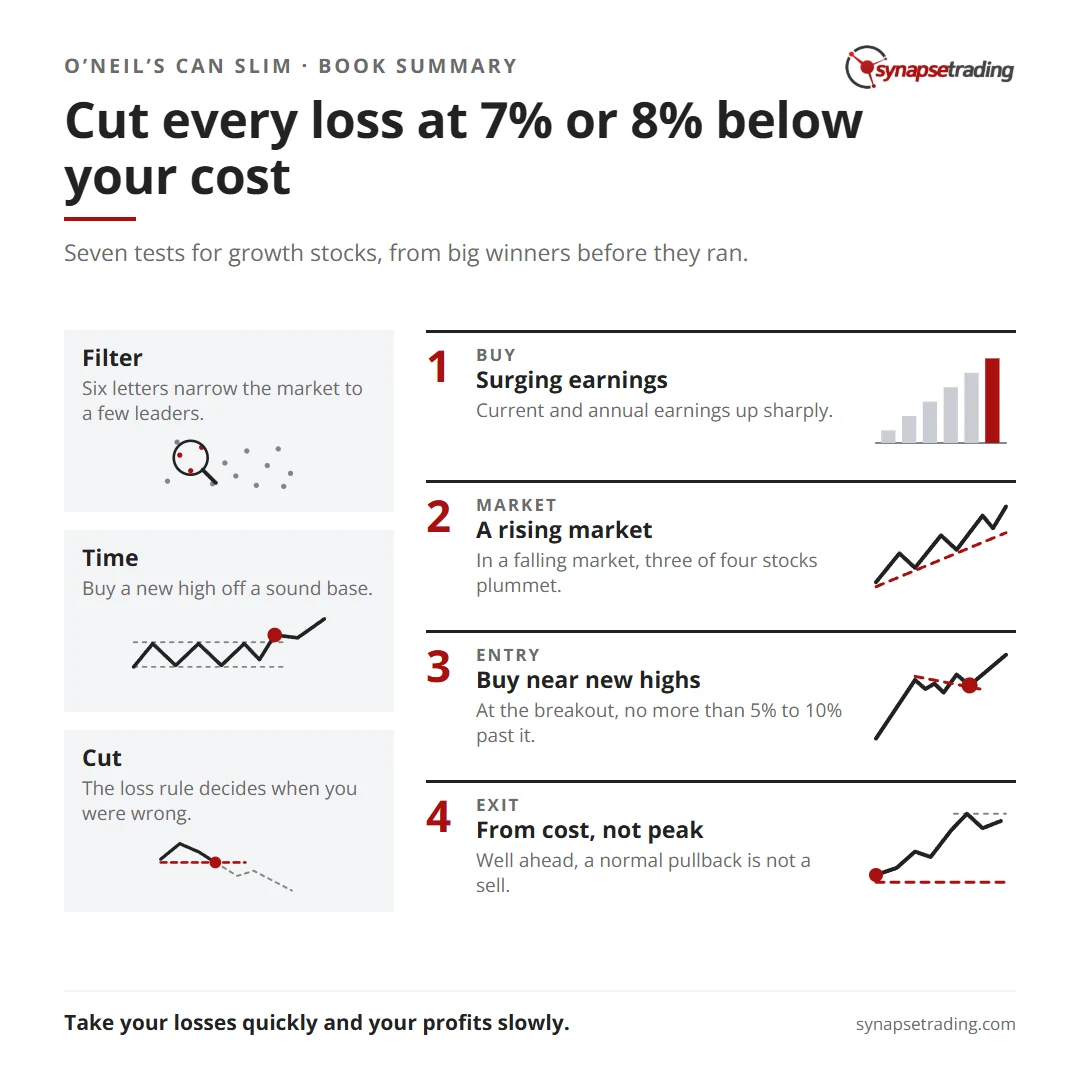
Cut every loss at 7% or 8% below your cost. Summary card for the post: How to Make Money in Stocks Summary: William O'Neil's CAN SLIM Rules.

Who is William O’Neil?

William J. O’Neil founded the research firm William O’Neil + Co. and the newspaper Investor’s Business Daily. He started small, with five shares of Procter & Gamble, and says the book “isn’t written for the elite.” It is written for ordinary savers who want a set of rules they can follow.

The edition summarised here is the fourth, published by McGraw-Hill in 2009. It opens on the market falls of 2000 and 2008.

What is the overview of the book?

The book has two main parts. Part I is about buying: a chapter on chart bases, then one chapter for each of the seven CAN SLIM letters. Part II is about being smart from the start: cutting losses, selling on the way up, money management and the 21 most common mistakes. Later chapters cover industry groups, reading the news and mutual funds.

The evidence is a long study. O’Neil’s firm took the greatest winner of each year across 125 years and charted what each looked like before its big move. His core belief is that the market is “human nature and crowd psychology on daily display.” Because human nature does not change, he argues the same price patterns keep coming back.

One caution before the rules. The study looks at winners chosen after the fact. It shows what the big winners looked like, but not how many stocks looked the same and then failed.

What does CAN SLIM stand for?

Each letter is a test. A stock has to pass all seven.

LetterWhat it meansThe book’s number
C: current quarterly earningsLatest quarter’s earnings per share up sharply on the same quarter a year agoAt least 25% to 50%. “A mediocre 10% or 12% isn’t enough.”
A: annual earningsEarnings up in each of the last three years25% or more a year, with return on equity of 17% or more
N: something newA new product, new management or new industry conditions, and a new price high off a sound baseOver 95% of the winners had something new
S: supply and demandFewer shares on offer, and big buying at the breakoutBreakout volume at least 40% to 50% above normal
L: leader or laggardBuy the number one stock in a leading groupRelative strength of 80 or higher
I: institutional sponsorshipA rising number of good funds owning the stockAt least one or two top-performing funds
M: market directionThe general market must be in an uptrendRead the index price and volume every day

O’Neil calls the change in earnings per share “the single most important element in stock selection today.” He says only about 2% of stocks show earnings growth that strong at any one time. So C alone throws out most of the market. On estimates he is just as firm: “Actual reported earnings are facts.”

How does CAN SLIM work as a system?

It helps to see the seven letters as three jobs.

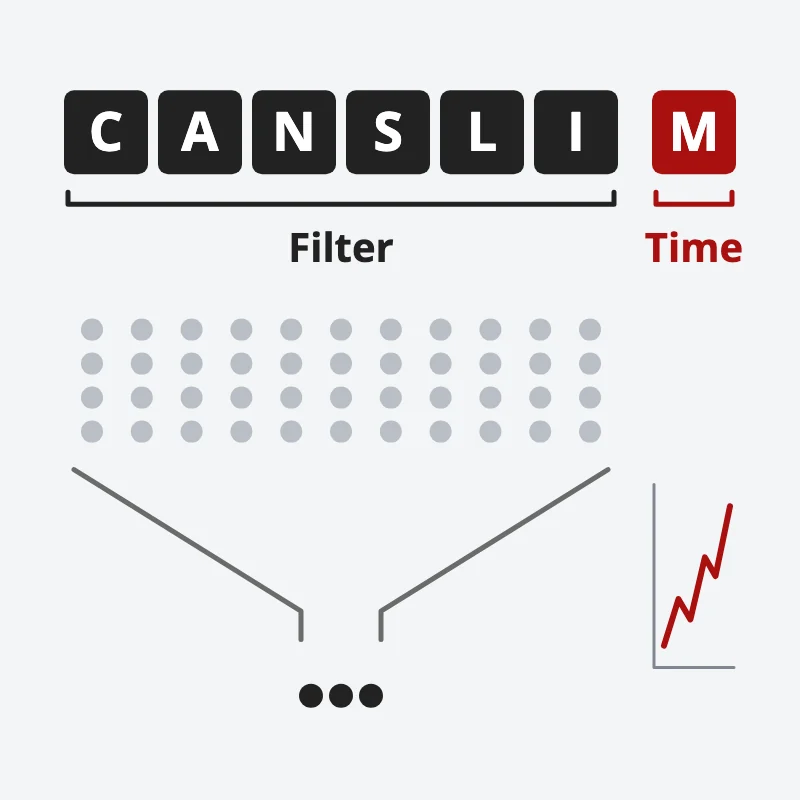
  1. Filter. C, A, N, S, L and I narrow the market down to a handful of leading companies with real earnings.
  2. Time. The new high off a sound base, and the M, decide when to buy. A good stock bought at the wrong moment still fails.
  3. Cut. The loss rule decides when you were wrong, and it never bends.

The timing job is the one most readers skip. O’Neil is blunt about M. Get the other six letters right in a falling market, and “three out of four of your stocks will plummet” with it.

The letters C, A, N, S, L and I filter many stocks down to a few leaders; the letter M, market direction, times the buy
Six CAN SLIM letters pick the stock; M, the market’s direction, decides when to buy.

Why does O’Neil buy stocks near their highs?

This is the part that feels wrong to most new investors. O’Neil calls it the Great Paradox: “What seems too high in price and risky to the majority usually goes higher eventually, and what seems low and cheap usually goes lower.”

So he buys a stock as it breaks to a new high out of a base, a stretch of sideways trading that lasts from seven or eight weeks to over a year. His favourite base is the cup with handle, which we break down in our guide to the cup and handle pattern. The buy is at the breakout, and no more than 5% to 10% past it, because a stock that has run further is likely to pull back and shake you out. As he puts it: “There’s a right time, and then there are all the other times.”

The same thinking makes him wary of cheap shares. “I prefer not to buy any common stock that sells for below $15 per share,” he writes, because most of his super winners broke out of bases between $30 and $50.

What is O’Neil’s 7% to 8% stop-loss rule?

Cut every loss when a stock falls 7% or 8% below what you paid. He calls it “an absolute maximum.” The reason is his own hit rate: “only one or two out of ten stocks that I’ve bought turned out to be truly outstanding.” The other eight have to be kept small, or they eat the winners.

Three details matter.

  • It runs from your cost, not the peak. “Do not sell a stock just because it’s off 7% to 8% from its peak price.” Once you are well ahead, a normal pullback is not a sell.
  • It caps your real risk. Follow it and, in his words, “It’s 8%, no matter what you buy.”
  • It stops the big loss early. “Every 50% loss began as a 10% or 20% loss.”

His summary is an old line: “take your losses quickly and your profits slowly.” I came to the same place in what I learnt in 15 years of trading. Once I accepted that half my trades would lose, a single loss stopped feeling like a verdict on me.

When does O’Neil take profits?

He found that most winners, after breaking out of a proper base, “tend to move up 20% to 25%” and then pull back to build a new base. So the plain rule is to take most gains at 20% to 25%, while the stock is still rising. “If you don’t sell early, you’ll be late.”

There is one big exception. If a stock jumps 20% in only one to three weeks after the breakout, hold it for at least eight weeks. Those are the ones that can become the big winners.

Put the two rules together and you get a ratio of about three to one between the profit target and the loss cut. O’Neil says winning comes from losing “the least amount possible” when you are wrong, not from being right all the time.

How many stocks should you own?

Fewer than most people think. “Wide diversification is a substitute for lack of knowledge,” he writes. He sets the number by account size, from two stocks in a small account to four or five in a mid-sized one, and six or seven even past a million dollars. If you want a sixth stock, sell the weakest of your five first.

If you want a checklist that sets your exit before you enter, our free 15-Minute Swing Trader’s Checklist lays it out. Get the free checklist →

Concluding thoughts

How to Make Money in Stocks is one of the few investing books that gives you numbers rather than opinions. Its best lesson is not a letter in CAN SLIM. It is the loss rule, and the idea that you will be wrong most of the time and can still do well.

O’Neil ends Part II with 21 mistakes, and the first behind them all: “By far the greatest mistake that 98% of all investors make” is never studying where their own buys and sells went wrong.

For his best one-liners, see our post on William O’Neil’s best trading tips and quotes. The book also sits on my reading list and in our guide to the best investing and trading books of all time.

So pick your last losing trade. How far did it fall below your cost before you sold it?

FAQ

What is the CAN SLIM method?

William O’Neil’s seven-part test for growth stocks: current earnings, annual earnings, something new, supply and demand, leader, institutional sponsorship and market direction.

What is O’Neil’s 7% to 8% rule?

Sell any stock that falls 7% or 8% below the price you paid, with no exceptions. The rule is measured from your cost, not from the stock’s peak.

Does O’Neil recommend buying stocks at new highs?

Yes, when the stock is breaking out of a sound base in a rising market. He avoids buying more than 5% to 10% past the breakout point.

When does CAN SLIM say to take profits?

Most gains at 20% to 25%. If a stock rises 20% within three weeks of breaking out, hold it for at least eight weeks.

Go deeper

O’Neil’s rules work because they are written down before the trade. The free 15-Minute Swing Trader’s Checklist does the same for swing traders: the daily scan, the questions to ask before you enter, and the five rules that keep you in the game.


About the author. Spencer Li is The 15-Minute Trader and the founder of Synapse Trading. He is a Certified Financial Technician (CFTe) with 15+ years of trading, run from 70+ countries. He holds a B.Acc and B.BM from SMU. Every trade he takes is public, dated, losses left in. He teaches low-risk swing trading in 15 minutes a day, one system for any market.

Educational content only, not personalised financial advice. Trading carries risk, including loss of capital. Past performance is not indicative of future results. Synapse Trading is not licensed or regulated by MAS.
by Spencer Li
https://synapsetrading.com/wp-content/uploads/2026/10/how-to-make-money-in-stocks-summary-card.webp 630 1200 Spencer Li https://synapsetrading.com/wp-content/uploads/2026/10/synapse-logo-horizontal-light.png Spencer Li2026-06-17 12:10:312026-08-18 18:48:27How to Make Money in Stocks Summary: William O’Neil’s CAN SLIM Rules
Spencer Li

CFTe vs CMT: Which Technical Analysis Certification Is Worth It?

Trading Foundations
CFTe vs CMT - careers

Levels, format, cost and timing side by side, from someone who sat the CFTe, plus the one thing neither exam can prove

Published: 17 October 2026 · Last updated: 12 August 2026 · By Spencer Li, CFTe


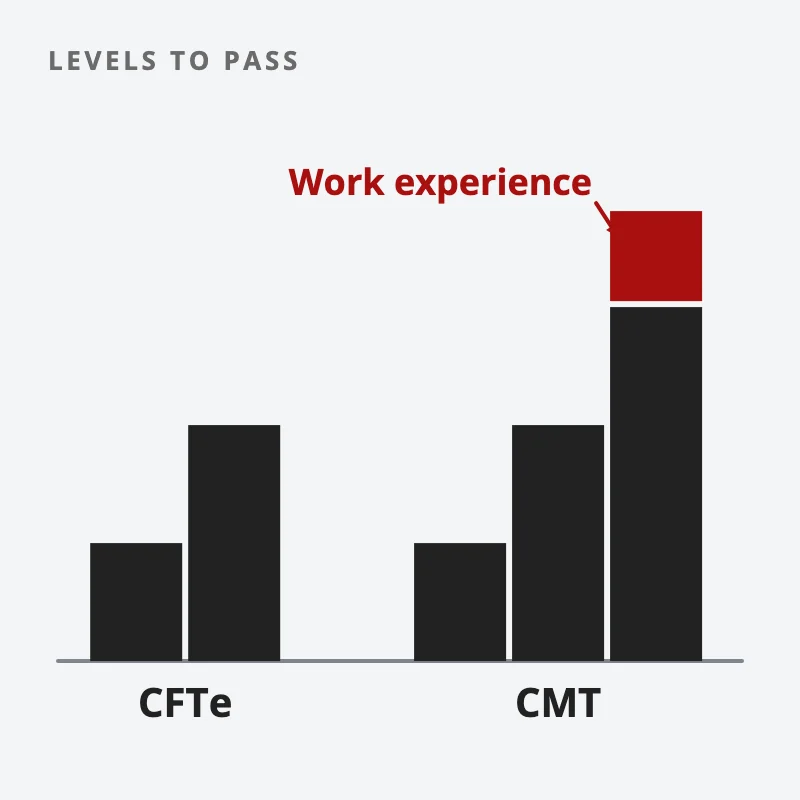
The CFTe and the CMT are the two main professional qualifications in technical analysis. The CFTe (Certified Financial Technician) is awarded by the International Federation of Technical Analysts (IFTA) and has two levels. The CMT (Chartered Market Technician) is awarded by the CMT Association in New York and has three levels, plus a work-experience requirement.

So which is worth it? If you work, or want to work, in the US industry, the CMT is the home-market qualification, and its work requirement is built for people already in a role. If you want an international qualification you can finish faster, on your own schedule, with a final exam where you analyse real charts in writing, the CFTe fits. And if you only want to trade your own money, neither is required. I hold the CFTe, and I will be straight about what it did and did not do for me.

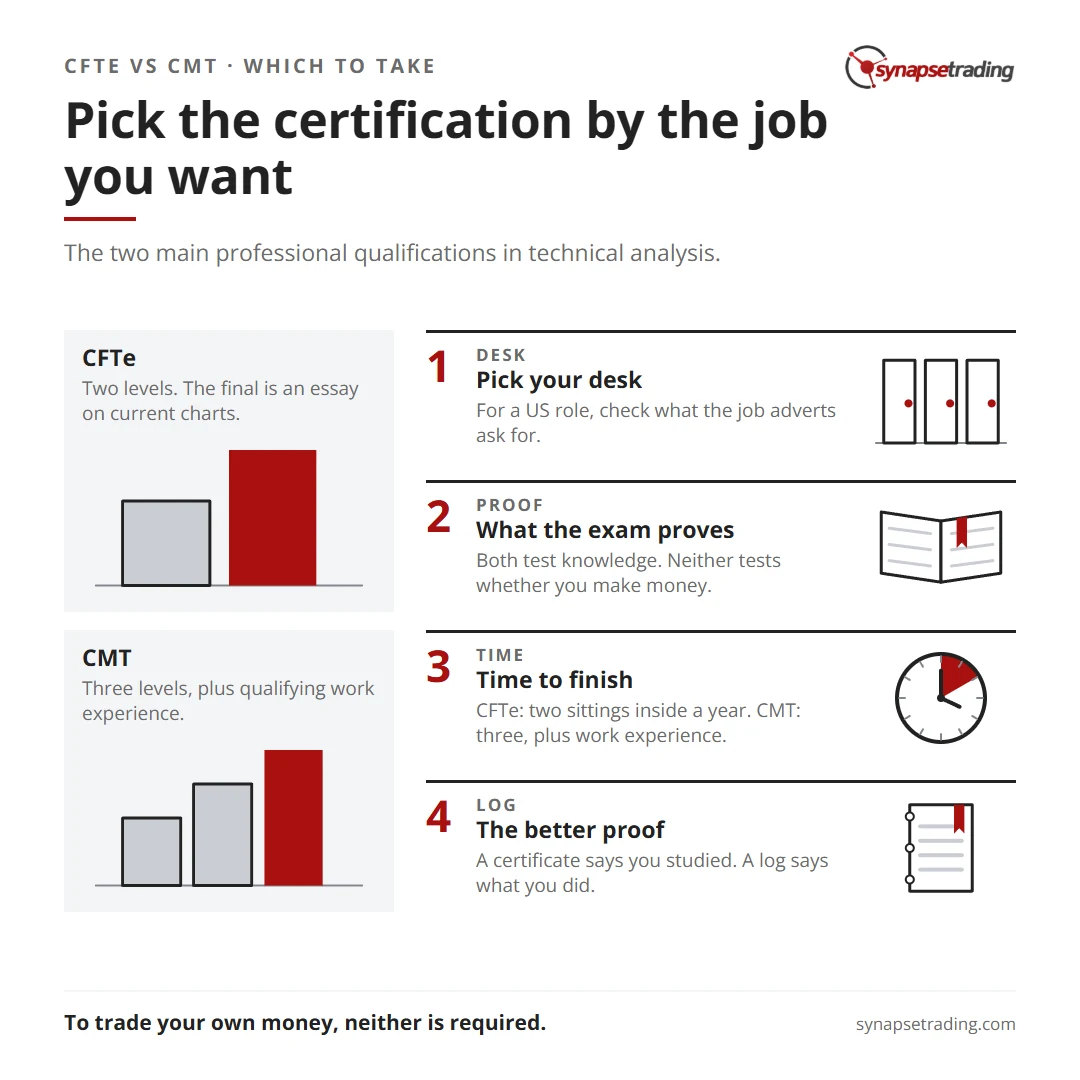
Pick the certification by the job you want. Summary card for the post: CFTe vs CMT: Which Technical Analysis Certification Is Worth It?.

What is the difference between the CFTe and the CMT?

Here they are side by side, from each body’s own pages as of October 2026.

CFTeCMT
Awarded byIFTA, a federation of national societiesCMT Association, New York
Levels23
First exam120 multiple-choice questions, any time of year at Pearson VUE centresLevel I, in set June and December windows
Final examEssay-based, analysing current charts on one market “as though for a Fund Manager”Level III
When you can sitLevel I all year, Level II in April and October, online via ZoomJune and December
Exam feesLevel I US$550 (members) or US$850, Level II US$850 or US$1,150, plus a US$100 proctor feeUS$875 early to US$1,475 late per registration for December 2026
Extra requirementNone beyond the two examsQualifying professional work experience and Professional Membership

Two rows matter more than the rest.

The first is the final exam. The CFTe’s second level is an essay. You get current charts and write up your analysis the way you would for a fund manager. That is closer to the actual job than another set of multiple-choice questions.

The second is the work requirement. To use the CMT letters, you need to pass all three levels and show qualifying professional work experience. If you trade from home, that can be the deciding row.

Two staircases: the CFTe with two levels, and the CMT with three levels plus a work-experience block on top
The CFTe has two levels; the CMT has three plus a work-experience requirement.

How much do the CFTe and the CMT cost?

Now the sums, in US dollars and exam fees only.

For the CFTe, a non-member pays US$850 for Level I, US$1,150 for Level II and the US$100 proctor fee, which comes to US$2,100. A member of an IFTA society pays US$550 and US$850 plus the proctor fee, which is US$1,500, before membership dues.

For the CMT, the December 2026 registration rates run from US$875 early to US$1,475 late. At early rates, three exams come to about US$2,625. Register late each time, and the same three cost about US$4,425.

So the CFTe is cheaper on fees alone, and it is faster to finish because Level I runs all year. The CMT costs more and takes at least three sittings, spread across the June and December windows.

How do you choose between them?

Three questions settle it for most people.

  1. Desk. Where do you want to work? If you are aiming at a US role, check which of the two the job adverts you want actually ask for, and let that decide. If you will trade your own account or work outside the US, the CFTe’s international recognition does the same job.
  2. Proof. What do you want the exam to prove? The CFTe’s written final tests whether you can analyse a live market and explain it. Both test knowledge. Neither tests whether you make money.
  3. Time. How fast do you need it? The CFTe can be done in two sittings inside a year. The CMT needs three, plus the work experience.

If you want the bigger picture of where these letters fit, the career in trading guide maps the four doors into the job, and the older career paths for the trading professional post lists the roles.

What was the CFTe like to sit?

I sat CFTe Level I in 2014 and passed with 86, against a pass mark of 74. I wrote at the time that I was “pretty sure I could have done better if I had studied for it.”

Level II was different. “It took me 2 whole weeks of serious studying/revising” to cover the syllabus, and I wrote about it in my post on passing the second level of the CFTe. IFTA says the programme “is designed for self-study”. There is no class to attend. You read, you practise on charts, you sit it.

Back then I compared it to seeing a doctor. You want to know the person treating you has a medical degree. A certification does the same for anyone teaching or managing money. It shows you studied the field properly.

But does a certification make you a better trader?

A trader on Reddit summed up the doubt in one line: “Tried every cliche setup (Head & Shoulders, CMT course). Read every book.”

That frustration is fair. Our career guide puts it this way: “A professional qualification such as the CFTe, which I hold, signals that you have studied technical analysis properly. It does not make a single trade win.”

The exam teaches you the language. Chart patterns, indicators, market structure, the theory behind each one. The technical indicators guide covers a lot of that same ground for free. What no exam can give you is a record of your own decisions under real risk.

That is why the better proof is a trade log. Ours is public: every trade since April 2024, dated, losses left in. A certificate says you studied. A log says what you did with it. If you want to build your own version, start with a trading journal that shows your edge.

If you are studying for either exam and want a simple daily routine to test what you learn on real charts, our free 15-Minute Swing Trader’s Checklist lays one out. Get the free checklist →

So which one should you take?

Pick by the job you want. For a US institutional desk, the CMT is the home-market qualification, and its work requirement fits people already in the industry. For an international qualification you can finish in under a year, on a written final that mirrors the real job, the CFTe fits. For trading your own account, both are optional, and a journal of real trades will teach you more per dollar.

Whichever you choose, ask yourself one question before you pay the fee. A year from now, what will you be able to show that you cannot show today?

FAQ

Is the CFTe or the CMT better?

Neither is better for everyone. The CMT is the US body’s qualification, has three levels and needs work experience. The CFTe is international, has two levels instead of three, and ends with a written chart analysis.

How long does it take to get the CFTe?

It can be done in two sittings inside a year, because Level I runs all year at Pearson VUE centres and Level II is offered in April and October.

How much does the CMT cost?

For December 2026, exam registration runs from US$875 early to US$1,475 late, so three levels at early rates come to about US$2,625 in exam fees.

Do I need work experience for the CMT?

Yes. Passing all three levels is not enough on its own. The CMT Association also requires qualifying professional work experience and Professional Membership.

Do I need a certification to trade my own money?

No. Neither qualification is required to trade your own account. They are most useful if you work in the industry or teach others.

Go deeper

Exams teach the theory. The free 15-Minute Swing Trader’s Checklist is how we turn it into a daily habit: the scan, the questions to ask before every trade, and the five rules that keep you in the game.


About the author. Spencer Li is The 15-Minute Trader and the founder of Synapse Trading. He is a Certified Financial Technician (CFTe) with 15+ years of trading, run from 70+ countries. He holds a B.Acc and B.BM from SMU. Every trade he takes is public, dated, losses left in. He teaches low-risk swing trading in 15 minutes a day, one system for any market.

Educational content only, not personalised financial advice. Trading carries risk, including loss of capital. Past performance is not indicative of future results. Synapse Trading is not licensed or regulated by MAS.
by Spencer Li
https://synapsetrading.com/wp-content/uploads/2026/10/cfte-vs-cmt-card.webp 630 1200 Spencer Li https://synapsetrading.com/wp-content/uploads/2026/10/synapse-logo-horizontal-light.png Spencer Li2026-05-31 21:15:482026-08-12 22:21:22CFTe vs CMT: Which Technical Analysis Certification Is Worth It?
Spencer Li

Prop Firm Challenges: How the Model Works, and 7 Red Flags to Check Before You Pay

Trading Foundations
Prop firm challenge red flags - prop trading

Last updated: 17 August 2026 · By Spencer Li, CFTe


A prop firm challenge is a paid trading test. You pay a fee, trade a simulated account toward a profit target, and try not to break any of the firm’s loss limits along the way. Pass, and the firm gives you a “funded” account with a profit split, which at most of these firms is still a simulated account rather than real money in the market.

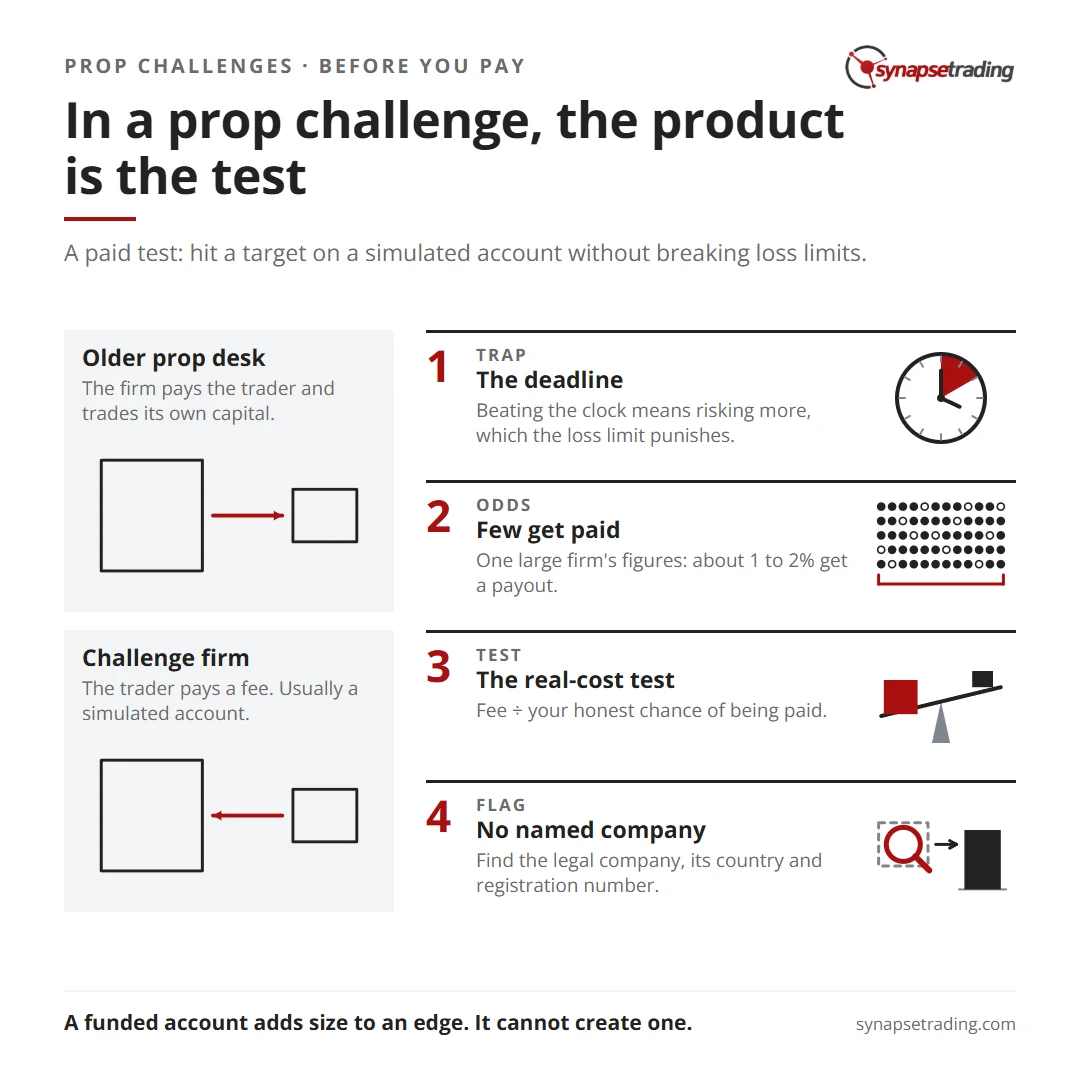
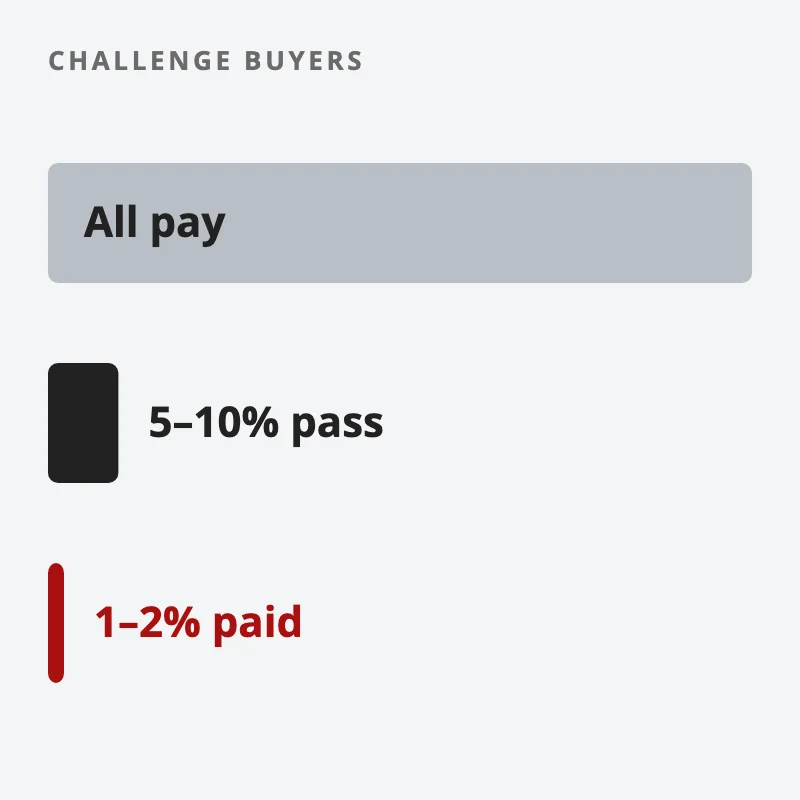
So the product being sold is the test itself. Everyone who enters pays the fee, and only a small group passes and then gets paid. By one large challenge firm’s own figures, only about 1 to 2% of the people who pay ever receive a payout.

That does not make every firm a scam. It does mean the odds and the rules matter far more than the account size on the advert. In this post, I’m going to cover how the challenge model works, what the published numbers say, and 7 red flags to check before you hand over a fee.

In a prop challenge, the product is the test. Summary card for the post: Prop Firm Challenges: How the Model Works, and 7 Red Flags to Check Before You Pay.

What is a prop firm, and why are there 2 kinds?

“Prop” is short for proprietary trading, which means a firm trading its own money. The older kind hires traders, hands them the firm’s capital and a risk limit, and shares the profit. I traded professionally for a few years, and on that kind of desk nobody paid to sit down. The firm only made money when its traders did.

The challenge model turns that around. The trader pays first, before a single trade is placed, and the firm collects that fee whether the trader passes or fails.

The older prop deskThe challenge firm
Who pays at the startThe firm pays the trader, often a small allowanceThe trader pays the firm a fee
Whose money is tradedThe firm’s own capital, in the real marketUsually a simulated account
How the firm earnsA share of the traders’ profitsChallenge fees from every entrant, plus a share of any profits
How you get inA record, an interview or a training programmeA credit card

How does a prop firm challenge work?

The details change from firm to firm, but most challenges are built from the same 6 parts. Read each one in the terms before you pay, because each one is a way to fail.

PartWhat it meansWhy it matters
Profit targetMake a set percentage on the account to passIt sets the pace you must trade at
Daily loss limitLose more than a set amount in one day and you failOne bad session ends the attempt
Maximum drawdownA floor the account can never touch. Some floors “trail” up behind your highest balanceA trailing floor rises with your profits, so the room you have to lose never grows
Time limit or minimum daysPass within a set period, or trade a minimum number of daysIt pushes you to trade when there is nothing to trade
Banned behaviourA list of strategies or habits the firm forbidsThe vaguer the list, the easier a payout is to refuse
Profit split and payout rulesHow profits are shared, and when you can withdrawExtra conditions can apply at payout time

So why do so many people fail a test that sounds simple?

Because the rules reward one kind of trader and the deadline pushes you to be another. Imagine a hypothetical trader with a real edge of +0.2R a trade, which means each trade makes 0.2 times the amount risked on average, and who risks 1% of the account on every trade. To make a 10% target, that trader needs about 50 trades on average (10 ÷ 0.2). If the time limit only leaves room for 15 good setups, the only way to hit the target in time is to risk more on each trade. And risking more on each trade is exactly what the daily loss limit punishes.

The deadline creates the fear of missing out, and that fear breaks the rules. A trader can have a real edge and still fail, simply by sizing up to beat a clock. If expectancy is new to you, the trading expectancy formula explains the R arithmetic above.

What are the real odds of getting paid?

Low, by the industry’s own numbers. In March 2025, Finance Magnates reported data from the chief executive of one large challenge firm: a challenge pass rate of 5 to 10%, and about 20% of those who passed going on to receive any payout. The outlet’s own arithmetic put the chance of a payout at “1–2%” for a typical customer.

Three bars to scale: every challenge buyer pays, 5 to 10% pass, and only 1 to 2% receive a payout
By one firm’s figures, everyone pays the fee and only 1 to 2% get paid.

A second dataset, from a company that builds technology for prop firms, puts it differently. In April 2026, Finance Magnates reported that this data “puts the share of prop participants who turn a profit at roughly 7%, with average earnings of just 4% of allocated capital.” The 2 figures measure slightly different things, so they do not have to match. Both say the typical buyer pays and does not get paid.

Now turn that into money. Say a challenge costs USD 500 (about SGD 641), a hypothetical but realistic fee. If your chance of ever reaching a payout is 2%, then on average it takes about 50 attempts to get one payout:

50 attempts × USD 500 = USD 25,000 in fees (about SGD 32,073)

That is the real cost of one payout at those odds, and the payout has to beat it before you are ahead. I call this the real-cost test: divide the fee by your honest chance of being paid. Do note that a skilled, patient trader has better odds than the average buyer, which brings the real cost down. But very few people buy their first challenge knowing their odds, and the advert never shows them.

This is the casino logic from trading versus gambling, with the trader sitting on the player’s side of the table.

If you want a daily routine built around your own account instead of a deadline, the free 15-Minute Swing Trader’s Checklist is at the end of this post.

What are the 7 red flags to check before you pay?

1. Is there a named company behind it?

Find the legal company, the country it is registered in, and its registration number. A firm that only shows a brand name and a chat window is asking you to trust a logo.

2. Is it on a regulator’s warning list?

In Singapore, search the firm on the MAS Investor Alert List. MAS describes it as a list of persons who “may be or may have been wrongly perceived as being licensed or in any other way authorised or regulated by MAS”.

But an empty search result proves very little. The page itself says, “This list is not exhaustive and is based on what was known to MAS at the time of publication.” In a 2022 reply in Parliament, MAS put it more bluntly: “This does not mean that all entities which are not listed on the IAL are safe to deal with.”

3. Can you check its payouts yourself?

In April 2026, Finance Magnates wrote that “Most prop firms still verify payouts through self-reported dashboards or on-chain crypto transfers, neither of which gives traders a reliable picture.” A payout record that an outside party has checked is worth more than a wall of happy faces.

4. Can the rules change after you pay?

They can, and they have. In July 2024, one firm announced a new rule that no more than 50% of a trader’s profits could come from a single trading day before a withdrawal. Traders pushed back hard, and the firm removed the rule about 2 weeks later. Check whether the terms say rules can change, and whether a change applies to accounts you have already paid for.

5. Is the banned-strategy list vague?

Words like “gambling”, “abuse” or “unfair trading”, with no definition, let the firm decide after the fact. In March 2024, one large firm paused all payouts for what it called a “self-imposed internal audit”, saying it would make sure payouts “do not violate the gambling policies we have in place.” Finance Magnates reported that many customers said they were refused without a reason. A good rule tells you in advance, in plain words, what a breach looks like.

6. Does the deadline force you to size up?

Run the arithmetic from earlier on your own numbers. If your normal risk per trade cannot reach the target inside the time limit, the challenge is asking you to trade a different strategy from the one you have tested.

7. Is the person recommending it paid to?

Many “best prop firm” lists earn a commission on every sign-up. Ask whether there is a referral code in the link. For the record, Synapse Trading takes no commission from any prop firm, and this post names none.

When does a challenge make sense?

Rarely as a first step. A funded account adds size to an edge you already have, and it cannot create the edge. The order that works is your own account first, with 100 to 200 logged trades and a losing streak you traded through by the rules, then a challenge if you still want more size. The full map of that path is in the practical guide to pursuing a career in trading.

Personally, I would rather see a student trade a small account of their own for a year than pay for 10 challenges. The small account teaches the one thing a simulation cannot, which is how you behave when the loss is real. And if a firm does refuse your payout, this post on denied payouts covers how to tell a genuine rule breach from a firm that simply does not want to pay.

So before your next challenge, what is your honest chance of reaching a payout? What does the fee cost once you divide it by that chance? And would you still pay it if the advert showed you those 2 numbers?

FAQ

How does a prop firm challenge work?

You pay a fee and trade a simulated account toward a profit target without breaking a daily loss limit, a maximum drawdown or a time limit. Pass, and you get a funded account with a profit split, usually still simulated.

Are prop firms legit?

Some run honestly, but the model earns from fees paid by every entrant. One large firm’s own data put the chance of a typical customer receiving a payout at about 1 to 2%.

What percentage of traders pass a prop firm challenge?

One large firm reported a pass rate of 5 to 10% in 2025, with about 20% of those who passed going on to receive a payout.

How do I check if a prop firm is regulated in Singapore?

Search it on the MAS Investor Alert List and the MAS Financial Institutions Directory. MAS says the alert list is not exhaustive, so a missing name is not proof that a firm is safe.

Go deeper

The free 15-Minute Swing Trader’s Checklist has the daily routine, the questions to ask before every trade, and the five rules that keep you in the game.


About the author. Spencer Li is The 15-Minute Trader and the founder of Synapse Trading. He is a Certified Financial Technician (CFTe) with 15+ years of trading, run from 70+ countries. He holds a B.Acc and B.BM from SMU. Every trade he takes is public, dated, losses left in. He teaches low-risk swing trading in 15 minutes a day, one system for any market.

Educational content only, not personalised financial advice. Trading carries risk, including loss of capital. Past performance is not indicative of future results. Synapse Trading is not licensed or regulated by MAS.
by Spencer Li
https://synapsetrading.com/wp-content/uploads/2026/10/prop-firm-challenge-card.webp 630 1200 Spencer Li https://synapsetrading.com/wp-content/uploads/2026/10/synapse-logo-horizontal-light.png Spencer Li2026-05-18 16:57:362026-08-17 21:20:02Prop Firm Challenges: How the Model Works, and 7 Red Flags to Check Before You Pay
Page 2 of 12‹1234›»

Free checklist

The 15-Minute Swing Trader’s Checklist

The daily and weekly routine I use to find, manage and review trades in about 15 minutes a day, on the record since 2014.

Get the free checklist

Topics

  • Trading foundations
  • Technical analysis
  • Strategies and systems
  • Risk and money
  • Trading psychology
  • Markets and products

Synapse Trading

Swing trading for busy professionals, in 15 minutes a day.

Start free

Learn

  • Start here
  • Free trading guides
  • Blog
  • Tools and resources

Programs

  • Trading Mastery Program
  • Daily trading signals
  • Student results
  • Public trade log

Company

  • About
  • Contact me
  • Partnerships
  • Disclaimer
  • Privacy policy
  • Terms & Conditions

Synapse Trading Pte Ltd
Registration No. 201316168H
WhatsApp +65-8897-1204
info@synapsetrading.com

Contact Us

Synapse Trading Pte Ltd
Registration No. 201316168H

Whatsapp: +65-8897-1204
Telegram: @iamrecneps
Email: info@synapsetrading.com

Links

Disclaimer
Privacy policy
Terms & Conditions
Contact us
Partnerships

© 2012-2026 Synapse Trading | All rights reserved. Educational content only, not personalised financial advice. Trading carries risk, including loss of capital. Past performance is not indicative of future results. Synapse Trading is not licensed or regulated by MAS.
  • Link to Facebook
  • Link to X
  • Link to Instagram
  • Link to Youtube
  • Link to LinkedIn
  • Link to Mail
Scroll to top Scroll to top Scroll to top