

5 Reasons Singaporeans May Never Retire Despite Working Harder, Checked Against the 2026 Numbers
Want the daily routine? Get the free 15-Minute Swing Trader’s Checklist. Get it free →
By Spencer Li, CFTe · Last updated: 26 October 2026
Working harder rarely fixes retirement in Singapore on its own, because the five forces that make it hard act on what your savings can buy, while a pay rise only changes how much you earn. Those forces are low returns on idle cash, a CPF system built as a floor and not a full plan, inflation, decades of property debt, and an ageing population that raises the cost of care. You cannot outwork any of them. You can understand them, and then put your savings and your skills to work against them.
I first wrote this in March 2017. Two of my predictions from that year turned out wrong, and I have marked both below, with the numbers that proved them wrong.
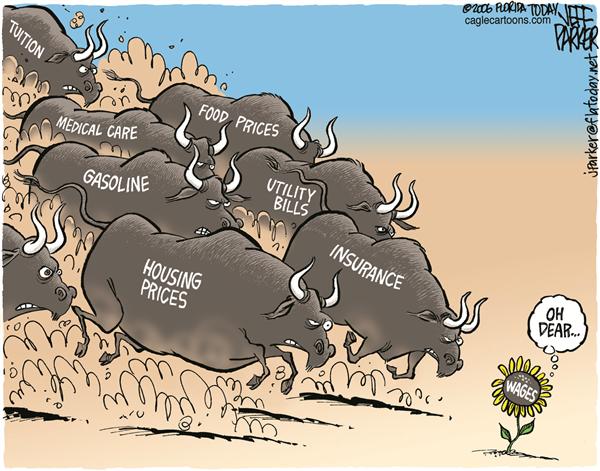 For most people, wages will never be enough to sustain their lifestyle at retirement.
Source: media.cagle.com
Why does working harder not solve it?
Talk to any taxi driver in Singapore and you will hear the same list within one ride. Healthcare costs more, petrol costs more, food costs more, a flat costs more, and the economy feels less steady than it used to. Most of those complaints are about prices. Very few are about pay.
That is the clue. Every extra hour you work raises the number on your payslip, but your retirement depends on what the money you save will buy in 20 or 30 years, and on how long it has to last. A pay rise does nothing about either of those on its own.
Before reaching for answers, then, it helps to see where the pressure comes from. There are five sources, and the first is the one most people never notice.
1. Why is money in the bank losing ground?
Singapore has more mobile phones than people, yet most of us could not say what our savings account paid last year. We are well educated and badly informed about our own money.
The trouble is simple. When the interest on your deposits is lower than inflation, every dollar you leave there buys a little less each year, and nobody sends you a statement showing the loss. To stand still you have to earn at least the inflation rate, and most bank deposits have not done that for long stretches.
So the first defence is financial literacy, and it does not need to be exotic. You do not need statistical arbitrage, options strategies or bets on the yield curve. You need the basics: the main financial instruments, the major asset classes, the difference between investing and speculating, and how to keep a single loss small. That alone puts you ahead of most people.
2. Is CPF enough to retire on?
Here is a number worth knowing before you turn 55. For members turning 55 in 2026, the Full Retirement Sum is $220,400, and CPF estimates it will pay about $1,780 a month from age 65 on the CPF LIFE Standard Plan, assuming 4% interest. The Basic Retirement Sum of $110,200 pays about $950 a month, and topping up to the Enhanced Retirement Sum of $440,800 pays about $3,440.
Now set that beside a working income. MOM puts the median gross monthly income from work of full-time employed residents at $5,775 in June 2025, including employer CPF. At the Full Retirement Sum, the payout is a little under a third of that median, so CPF covers the basics, and the lifestyle on top is up to you.
The interest side matters too. For October to December 2026, the CPF Ordinary Account pays 2.5% and the Special, MediSave and Retirement Accounts pay 4%. In 2017 I wrote that inflation runs at 4% to 5% in boom years, which leaves the Ordinary Account behind. SingStat’s figures back the shape of that. Inflation was 4.6% in 2012, 6.1% in 2022 and 4.8% in 2023. But it was also 2.4% in 2024 and 0.9% in 2025, when 2.5% came out ahead.
CPF is a solid floor. I would build on it and not stop there. Owning a smaller home later, holding dividend stocks or keeping some money in safer deposits all help you keep what you have, but none of them is a plan for making it grow.
That week in 2017, I was running a refresher on trading setups for my students.
If you want a way to keep learning without giving up your evenings, my free 15-minute swing trader checklist is the daily routine I use myself.
3. Did zero inflation become the norm?
This is the first place I was wrong. In 2017, Singapore had just been through two years of falling prices. SingStat’s index shows consumer prices down 0.5% in 2015 and again in 2016, and I wrote that zero inflation could become the norm and drag wages down with it.
 Inflation has fallen and fallen, and has even turned negative in 2015 and part of 2016.
Source: tradingeconomics.com
The chart above stops in 2016, and the years after it did not follow the script. Prices rose 0.6% in 2017, then 6.1% in 2022 and 4.8% in 2023, before cooling to 0.9% in 2025. The latest monthly reading puts prices 2.2% higher in September 2026 than a year earlier. Zero inflation was a passing episode.
My second miss was wages. I warned that stagnating or falling pay could become the norm. MOM’s 2025 report shows the opposite at the middle. Median income from work, after inflation, grew 2.1% a year from 2015 to 2025, and the bottom fifth of earners did better still, at 2.9% a year. I also listed jobs I expected to shrink, from marketing to logistics, based on 2016 surveys that I would not lean on today, so I have taken that list out.
What survived from that section is the warning about one salary doing all the work. Pay grew, and so did prices, sometimes faster in a single year. If your savings only keep pace with the salary that feeds them, you are running in place. A second skill that does not depend on one employer is still worth building, and so is the habit of helping your children follow what employers want next, alongside their exam scores.
4. Why do property prices push retirement further away?
If you already own a home, rising prices feel like good news. If you are trying to buy one, they mean a loan that runs for decades and a big slice of your working life spent paying it down.
Singapore’s stability is part of what draws overseas buyers, and that demand does not fade on its own. Most households end up carrying a mortgage through their best earning years, and a household paying off a home tends to spend and invest less. Spread across a generation, that debt slows growth for the whole economy, so the growth of the 1980s and 1990s is hard to repeat.
For retirement, the cost is simple. Every year spent mostly paying off a home is a year with less left over to put to work.
The same week I wrote the first version of this, I was the opening speaker at SMART Expo Singapore 2017.
5. Who pays for care when the country gets older?
Demographers use a blunt number called the old-age support ratio, which counts working-age people for every person aged 65 and over. In 1990, Singapore had 10.5 residents aged 20 to 64 for every resident 65 or older. By 2015 it was 5.7. In 2026 it is 3.2.
That is the problem in one line. In 2026, 19.5% of residents are 65 or older, against 11.8% in 2015, and fewer working adults stand behind each of them. It is the same greying that Japan has lived with for years, and it is nobody’s fault, since a lower birth rate does it on its own.
People are also living longer. A resident who reached 65 in 2025 could expect about 21.6 more years on average, with men at 19.9 and women at 23.1. Add a little inflation to two decades of retirement and the sums move quickly. At 2% a year, prices rise by about half over 21 years, so the same basket that cost $1,000 at 65 costs about $1,500 at 86.
More elderly people means more demand for doctors, beds and care, with fewer workers paying in. In 2017 I called this falling government support, which was not fair. Support has not been cut. The pressure comes from the arithmetic of an older population, and medical bills tend to follow it.
Is it really that bleak?
On 27 May 2026, a member of Reddit’s r/singaporefi pushed back on the gloom with a post titled “You could probably RE earlier than you think.” RE is short for retire early. Their point was that retirement money arrives in stages: their own savings first, then whatever CPF releases at 55, then the CPF LIFE payouts from 65. They had been waiting for one big number when several smaller ones would do.
They are right, and it corrects something in my 2017 version, which treated retirement as a single finish line that most people would never reach. For many people the honest answer is that you will retire, just later, or in stages, or on less than you hoped, unless you plan for each stage.
The five forces still decide how big each stage is. That is why the useful question is what you can control.
So what should you actually do?
None of these five forces will change because you work later at the office. What you can change is what your savings do while you work, and that starts with learning how markets behave.
Start small and start now. Learn the basics, then put a small amount you can afford to learn with into the market, and keep each loss small enough to shrug off. The goal is to stop leaving your money defenceless against forces that never take a day off. Shortcuts are not the goal.
When I started, the hardest part was keeping the habit going after work. A short daily routine solved that for me, and the free 15-minute swing trader checklist is the one I still run.
For the beginner’s path in order, start with my free trading guides. If you want to see what a big target needs each month, read how much you must save to have $1 million at retirement. And before you plan, learn from people who have already been there, in the 3 biggest financial regrets of retirees in Singapore. To see where your pay sits today, look at what you need to earn to be above Singapore’s average.
FAQ
Is CPF enough to retire on in Singapore?
For most people it is a floor. For members turning 55 in 2026, CPF estimates the Full Retirement Sum of $220,400 will pay about $1,780 a month from 65 on the Standard Plan. That is a little under a third of the June 2025 median income from work, so most people need savings on top.
What is the CPF Full Retirement Sum in 2026?
For members turning 55 in 2026, it is $220,400. The Basic Retirement Sum is $110,200 and the Enhanced Retirement Sum is $440,800.
What are the CPF interest rates now?
From 1 October to 31 December 2026, the Ordinary Account pays 2.5% and the Special, MediSave and Retirement Accounts pay 4%, according to CPF.
How long does retirement last in Singapore?
A resident aged 65 in 2025 could expect to live about 21.6 more years on average, according to SingStat. Women at 65 could expect 23.1 years and men 19.9.
Has Singapore’s inflation been higher than CPF interest?
In some years. SingStat shows inflation of 6.1% in 2022 and 4.8% in 2023, above the Ordinary Account’s 2.5%. In 2025 it was 0.9%, below it.
Does working harder solve the retirement problem?
Rarely on its own. The main pressures act on what your money buys and how long it must last, so learning to grow your savings matters as much as earning more.
Which of the five worries you most, and has any of them changed your plans? Let me know in the comments.
And if you want a routine that fits around a full-time job in 15 minutes a day, grab the free 15-minute swing trader checklist.
About the author. Spencer Li is The 15-Minute Trader and the founder of Synapse Trading. He is a Certified Financial Technician (CFTe) with 15+ years of trading, run from 70+ countries. He holds a B.Acc and B.BM from SMU. Every trade he takes is public, dated, losses left in. He teaches rules-based swing trading in 15 minutes a day, one system for any market.
Education, not financial advice. Synapse Trading is not licensed by MAS to advise on investment products. Trading carries risk of loss, and past performance is not indicative of future results.
Want the daily routine? Enter your email for the free 15-Minute Swing Trader's Checklist.
Free 5-page PDF, then occasional trading emails. Education only, not financial advice. Unsubscribe anytime. Kit stores your email in the US: see our privacy policy.
Want to learn the full method? The Trading Mastery Program teaches the 4 strategies I have traded since 2011. It suits beginners and experienced traders.
Rather follow the trades as they happen? Daily Trading Signals is our Telegram channel: my trade ideas with entry, stop and exit, and every trade is public.
Questions about this post? Ask in the free Telegram channel →
Educational content only, not personalised financial advice. Trading carries risk, including loss of capital. Past performance is not indicative of future results. Synapse Trading is not licensed or regulated by MAS.

