

3 Practical Tips for Early Financial Freedom: Read the Cycle, Keep Cash Ready, Learn Early
Want the daily routine? Get the free 15-Minute Swing Trader’s Checklist. Get it free →
By Spencer Li, CFTe · Last updated: 26 October 2026
If you want financial freedom early, three habits do most of the work. You read the big market cycles instead of the daily wiggles, you keep a war chest of cash ready for the day prices turn cheap, and you learn the skills early, while mistakes are still small. I first gave these three tips to new investors at the SGX Investment Carnival in February 2015. None of them is a shortcut, and none comes with a date attached, but together they put time and patience on your side.
Eleven years on, I reread my notes from that talk. Two of the tips have aged well, and one of the calls I made inside tip one aged quite badly, so I will show you that too.
What did I tell new investors at the SGX Investment Carnival?
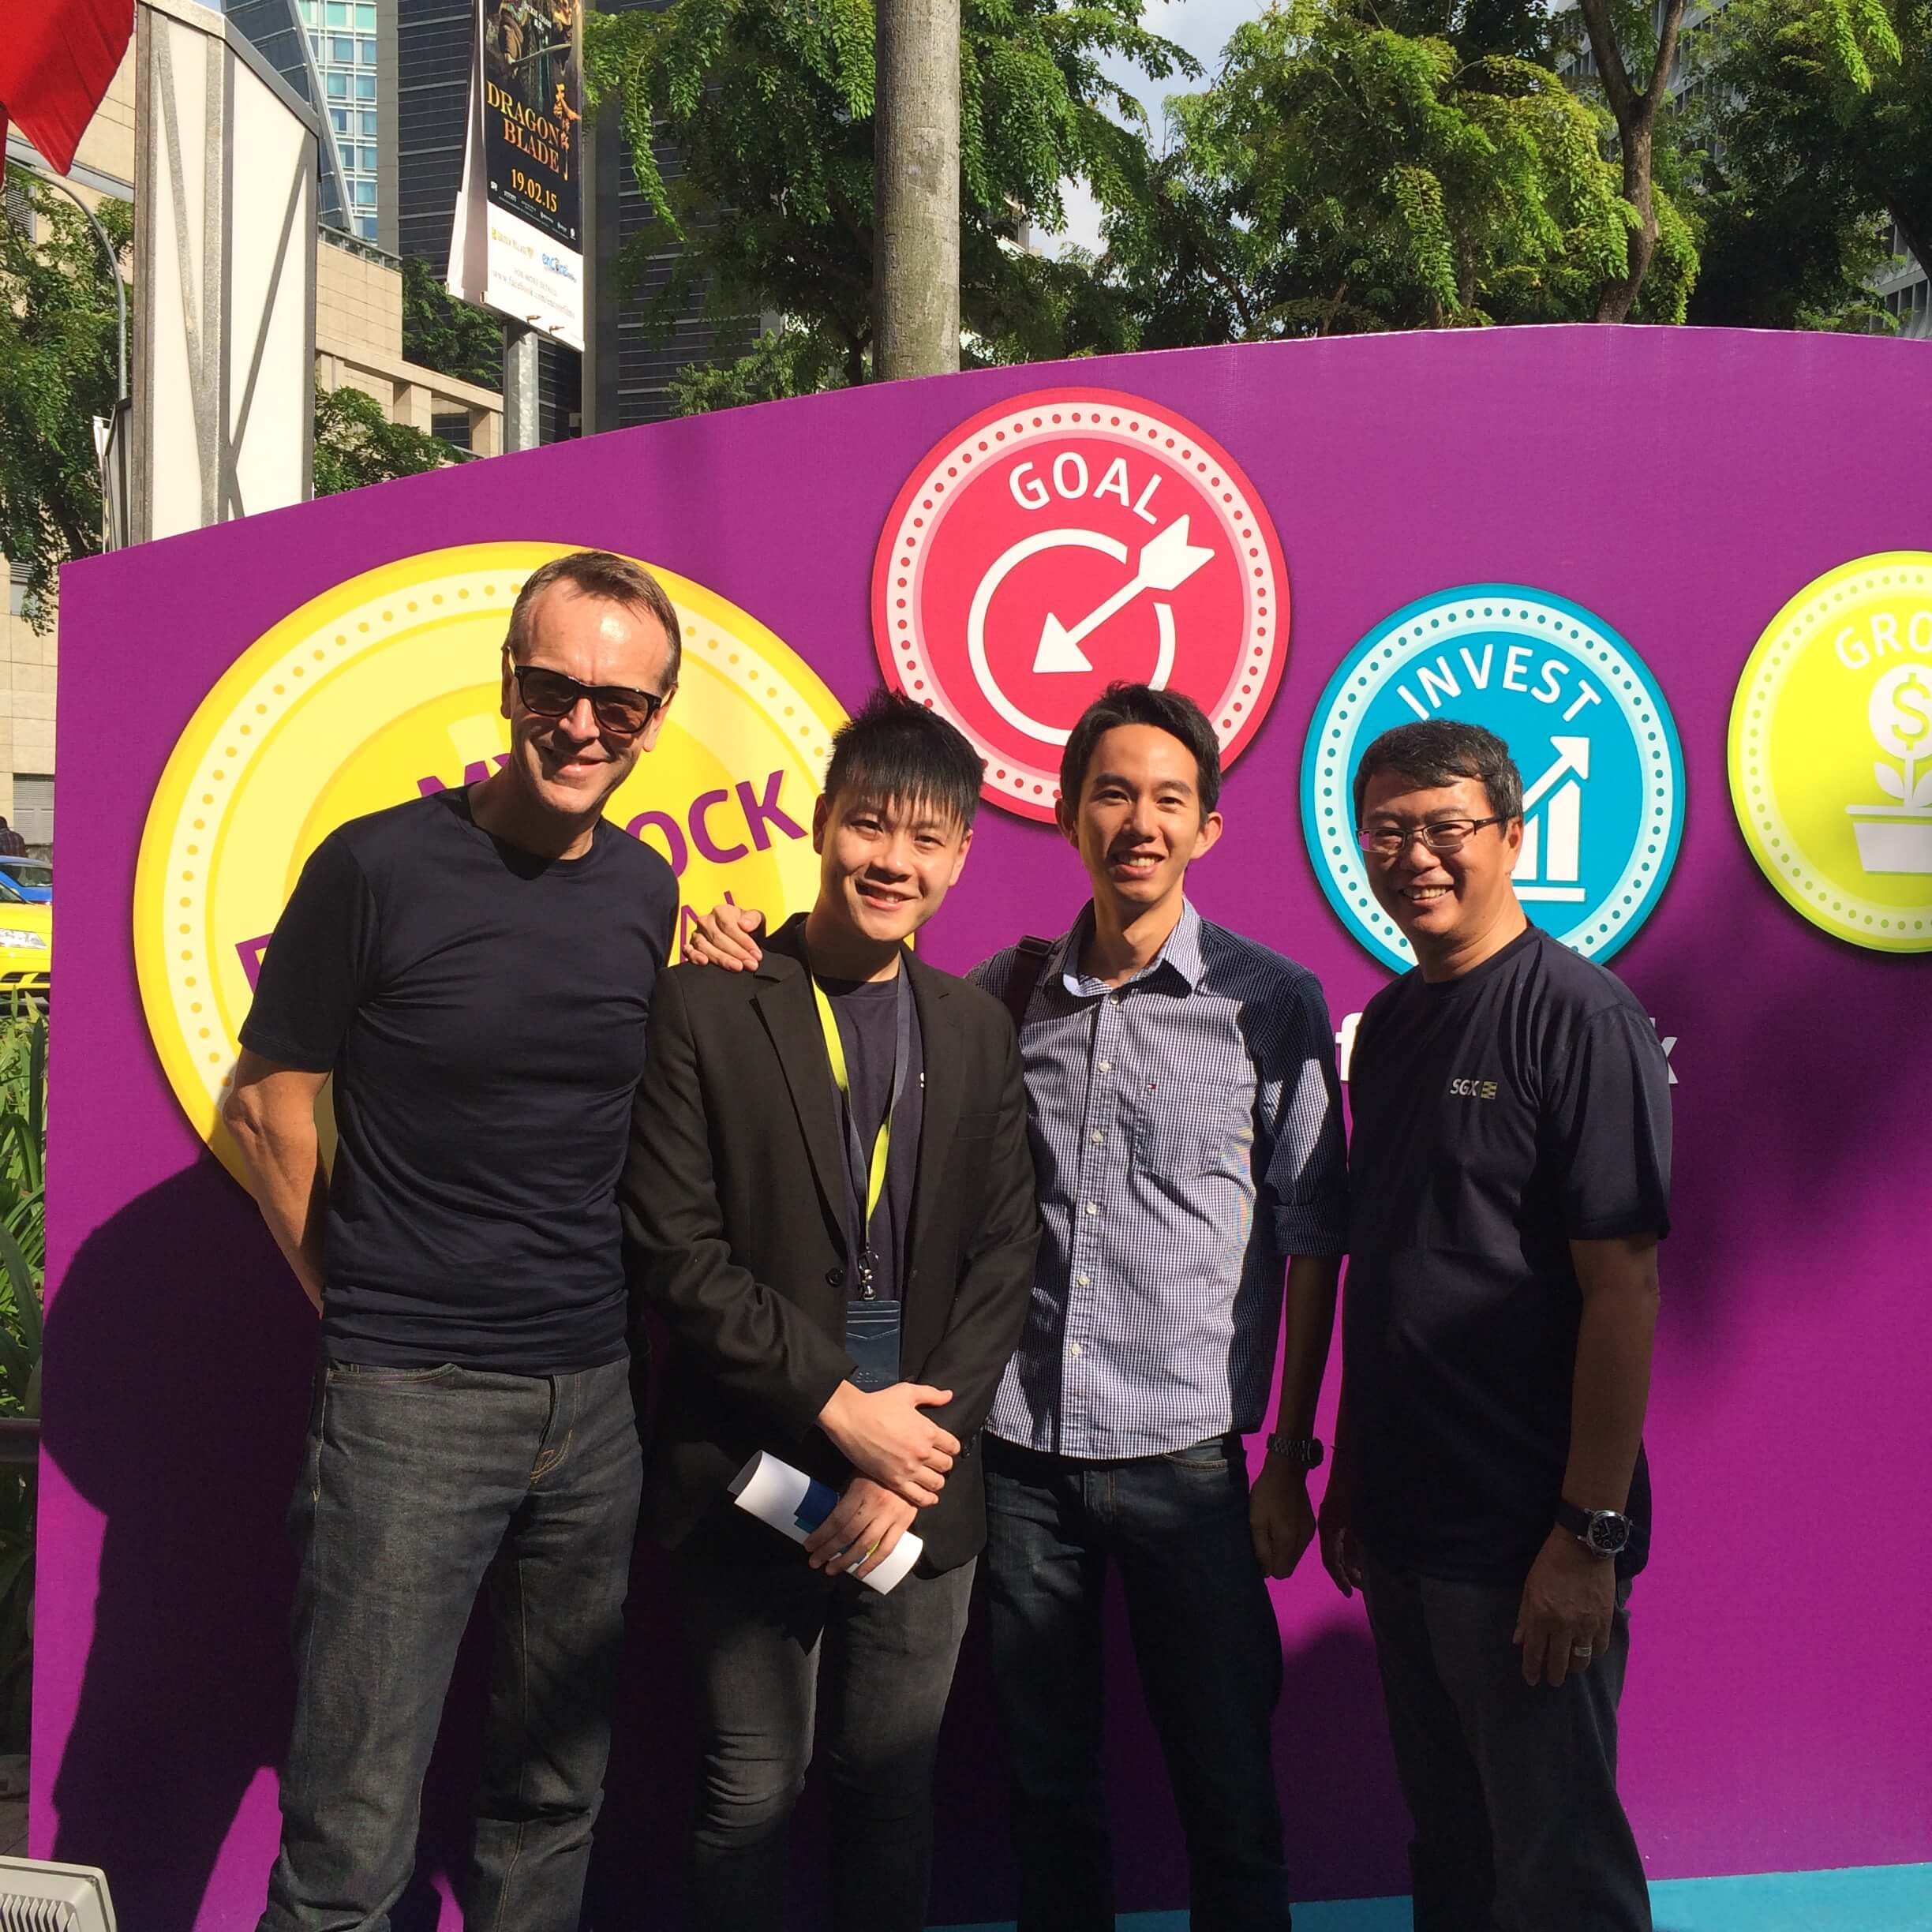
On Saturday, 7 February 2015, SGX invited me to share my trading journey with a room of new investors and traders. I had a short slot, so I picked the three tips that I felt had made the biggest difference for me, and left everything else out.
After the talk I ended up in a casual photo with Magnus Böcker, who ran the Singapore Exchange as its chief executive from December 2009 to June 2015, and his staff.
What strikes me now is how plain the three tips were. Nobody in that room needed a secret indicator. They needed a way to think about when to buy, where the money would come from, and how to learn without paying too much for the lessons.
Can you really time the market?
You have probably heard that it is impossible to time the market, and for the daily market I would agree. Trying to guess next Tuesday is a fairly reliable way to give your money to someone else.
The big cycles are a different story. Warren Buffett put it most famously in his 1986 letter to Berkshire Hathaway shareholders: “we simply attempt to be fearful when others are greedy and to be greedy only when others are fearful.” Strip away the poetry and it says that cheap things are worth buying when everyone is scared of them, and that expensive things are worth trimming when everyone is euphoric.
So in 2015 I asked the room a simple question. What is at the cycle low, or cheap, right now?
Then I showed them the stock market’s rough 10-year rhythm of stress, “1997, 2007, … What’s next?” I told them nobody could predict a crash. But I also said I was sure that “now is NOT the low point in the stock market cycle”, and that “my money is on commodities like oil, gold and silver.”
Here is what the oil price did next. This part is my addition, from the US Energy Information Administration’s daily data, and it was not in the talk. West Texas crude closed at $51.66 a barrel on Friday, 6 February 2015, the day before the carnival. By 11 February 2016, a year later, it had fallen to $26.19.
That is a drop of about 49%. Put another way, anyone who bought at $51.66 needed the price to almost double from that low just to get back to where they started.
So the commodity call was early, by at least a year. The 10-year rhythm did not keep its appointment either. The next big fall in stocks came in early 2020, when the pandemic hit, 13 years after 2007 rather than 10.
Do note that I am not telling you this to be modest. It shows the real limit of cycle reading. Cycles tell you roughly where you are, and they are very bad at telling you when. The habit worth keeping from that talk is the question, which asks where an asset sits in its long cycle, together with the patience to wait when nothing is cheap. If you want a closer look at one cycle signal that traders watch, I wrote about the inverted yield curve and recessions.
How do you build a war chest fast enough to matter?
My second tip opened with a question I still like: “If the market crashes tomorrow, do you have the capital to take advantage of the opportunity?”
For most people starting out, the honest answer is no. A war chest is simply a pool of cash you keep ready to deploy when prices get cheap, and in 2015 I walked through the three usual ways of building one.
| Route | How it works | Speed | The catch |
|---|---|---|---|
| Work and save | Earn, spend less, bank the difference | Slow, about 5 to 10 years by my 2015 estimate | Good opportunities can pass while you are still saving |
| Start a business | Build something that throws off cash | Fast, if it works | Plenty of new businesses close in their first few years |
| A small trading portfolio | Put a small slice of capital into trades you manage yourself | Depends entirely on skill | Without skill and risk control, it goes backwards quickly |
Personally, I took the third route, and in 2015 I suggested it to the room as well. The point of the small portfolio was to learn with real trades while keeping the amount at risk small, and it took me about 15 minutes a day to manage. It is also the route with the most ways to hurt yourself, which is why the size of each trade matters more than the trade itself. My guide to position sizing and money management covers why.
In April 2026, a trader on Reddit’s r/singaporefi asked a fair question after a scary week in the markets. They asked who had actually managed to deploy their war chest to “buy the dip”, and admitted that they had not: “emergency funds are emergency funds.”
They are right, and my 2015 talk missed it. I treated savings and the war chest as one pot. An emergency fund is there for your life, such as a lost job, a hospital bill or a family crisis. A war chest is there for prices. If both live in the same account, fear usually wins, because spending the money that protects your family on a falling market feels like gambling with the rent. So the two belong in separate places, and only one of them is ever meant to be spent on a crash.
If you would like a short daily routine to go with that, the free 15-minute swing trader checklist is the one I use myself.
Why is waiting so hard, even when you know the plan?
Around 1970, psychologists at Stanford, led by Walter Mischel, offered preschool children a small treat now, or two if they could wait. This became the famous marshmallow test. A 1990 follow-up by Shoda, Mischel and Peake reported that the children who waited longer did better as teenagers, and the popular story became that patience is a trait you either have or lack.
In 2018, the researchers Watts, Duncan and Quan repeated the idea with a much larger group of children, most of them from families where the mother had not finished college, and published it in Psychological Science. The link between waiting at age 4 and school achievement at 15 was still there, but it was only half the size of the original. Once they controlled for family background, early cognitive ability and the home environment, it shrank by another two thirds.
A smaller study from 2013 adds a twist. A team at the University of Rochester led by Celeste Kidd ran the same test with 28 children. First, they showed half of them that the adult running the test was reliable, and the other half that the adult was not. The children in the reliable group waited significantly longer. In the authors’ words, waiting may reflect “beliefs about the stability of the world” as well as self-control.
Hence, a large part of patience is how safe waiting feels. A war chest kept apart from your emergency money is what makes waiting feel safe. When you know your rent and your family are covered, holding cash through a boring market costs you very little, and so does spending it when everyone else is panicking.
What skills should you learn first?
The third tip was the simplest one. Learn the right skills early, because, as I said at the end of the talk, “the earlier you start, the more powerful the compounding effect is going to work in your favour.”
Compounding usually gets explained with money, but it works on skill too. Every mistake you make on a small account teaches you something that a large account would have charged you much more for. So the time to get your beginner mistakes out of the way is when the stakes are tiny, or on paper, long before you have a real war chest to protect.
Most of the starting material costs nothing. Books are still the cheapest teachers I know, and I keep my reading list of trading and investing books up to date. If you are new to charts, start with my beginner’s guide to trading and technical analysis, and my free trading guides collect the rest.
One thing I would add to the 2015 version. These days I keep buying after a crash in a separate lane from my swing trades. Buying cheap is a patient, long-term move that pays over quarters or years, while swing trades run on their own rules, and mixing the two tends to make both worse.
Learning is easier when it is a routine rather than a mood, and the free 15-minute swing trader checklist is the routine I run every day.
FAQ
What are the 3 practical tips for early financial freedom?
Read the big market cycles instead of the daily moves, keep a war chest of cash ready for when prices get cheap, and learn the skills early, while mistakes are still small. I first shared them at the SGX Investment Carnival in February 2015.
Can you really time the market?
You cannot do it day to day. You can judge roughly where an asset sits in its long cycle, cheap or expensive, but the timing of a turn is very hard to call. My own 2015 commodity call was early by at least a year.
What is a war chest in investing?
It is a pool of cash kept ready to deploy when prices fall and assets get cheap. It is separate from an emergency fund, which is there for job loss, medical bills and other life events.
Should my emergency fund be my war chest?
No. Keep them apart. Money that protects your family is very hard to spend in a falling market, so a war chest only works if it is money you can afford to put to work.
Why does starting early matter so much?
Because compounding needs time, and that is true of skills as well as money. Mistakes made early, on a small account, are the cheapest lessons you will ever get.
So, which of the three is your gap right now, the cycle read, the war chest, or the skill? And if you keep a war chest, is it really separate from your emergency fund? Let me know in the comments.
If you have been wondering why so many young Singaporeans expect never to retire, I looked at that survey in this post on retirement worries.
And if you want a daily routine that fits around a full-time job, grab the free 15-minute swing trader checklist.
About the author. Spencer Li is The 15-Minute Trader and the founder of Synapse Trading. He is a Certified Financial Technician (CFTe) with 15+ years of trading, run from 70+ countries. He holds a B.Acc and B.BM from SMU. Every trade he takes is public, dated, losses left in. He teaches rules-based swing trading in 15 minutes a day, one system for any market.
Education, not financial advice. Synapse Trading is not licensed by MAS to advise on investment products. Trading carries risk of loss, and past performance is not indicative of future results.
Want the daily routine? Enter your email for the free 15-Minute Swing Trader's Checklist.
Free 5-page PDF, then occasional trading emails. Education only, not financial advice. Unsubscribe anytime. Kit stores your email in the US: see our privacy policy.
Want to learn the full method? The Trading Mastery Program teaches the 4 strategies I have traded since 2011. It suits beginners and experienced traders.
Rather follow the trades as they happen? Daily Trading Signals is our Telegram channel: my trade ideas with entry, stop and exit, and every trade is public.
Questions about this post? Ask in the free Telegram channel →
Educational content only, not personalised financial advice. Trading carries risk, including loss of capital. Past performance is not indicative of future results. Synapse Trading is not licensed or regulated by MAS.

